

The summer months of 2024 have proved eventful with early general elections in the UK where the Labour party won a large majority on a third of the vote. In France too, a left-wing coalition gained seats in the Assembly Nationale over incumbent President Macron’s centrist UMP. Iran held a presidential election, after the untimely death in a helicopter crash of former President Ebrahim Raisi. They have now elected Masoud Pezeshkian as president who is considered politically moderate in comparison. His presidency comes at a time when revenge is expected by many over military strikes by Israel in Iran, Syria and skirmishes in Hezbollah controlled areas of Lebanon, a proxy group supported by the Iranian regime.
The 2024 US Presidential campaign also has provided plenty of drama with the assassination attempt on Republican Party candidate ex-president Donald Trump. In addition, the incumbent president Joe Biden stepped down from the Democratic Party nomination in favour of his vice-president. The polls depict it’s still close, but Kamala Harris is ahead in key swing states like Pennsylvania.
Further occupying people’s attention have been major sporting events like the Paris Olympics, European Football Champions and the usual tennis, golf, motorsports and summer rugby tours. If sport isn’t one’s interest, there’s been much concern expressed over violent immigration and socio-religious based riots in the UK. Where politicians and pundits, including Elon Musk, commented over their viciousness, underlying causes and punishments meted-out in their aftermath.
The wars in the Ukraine, Middle East, South Sudan and Tigray province in Ethiopia all continue to rage. All worthy of comment and attention on their own account where resolutions are urgently required.
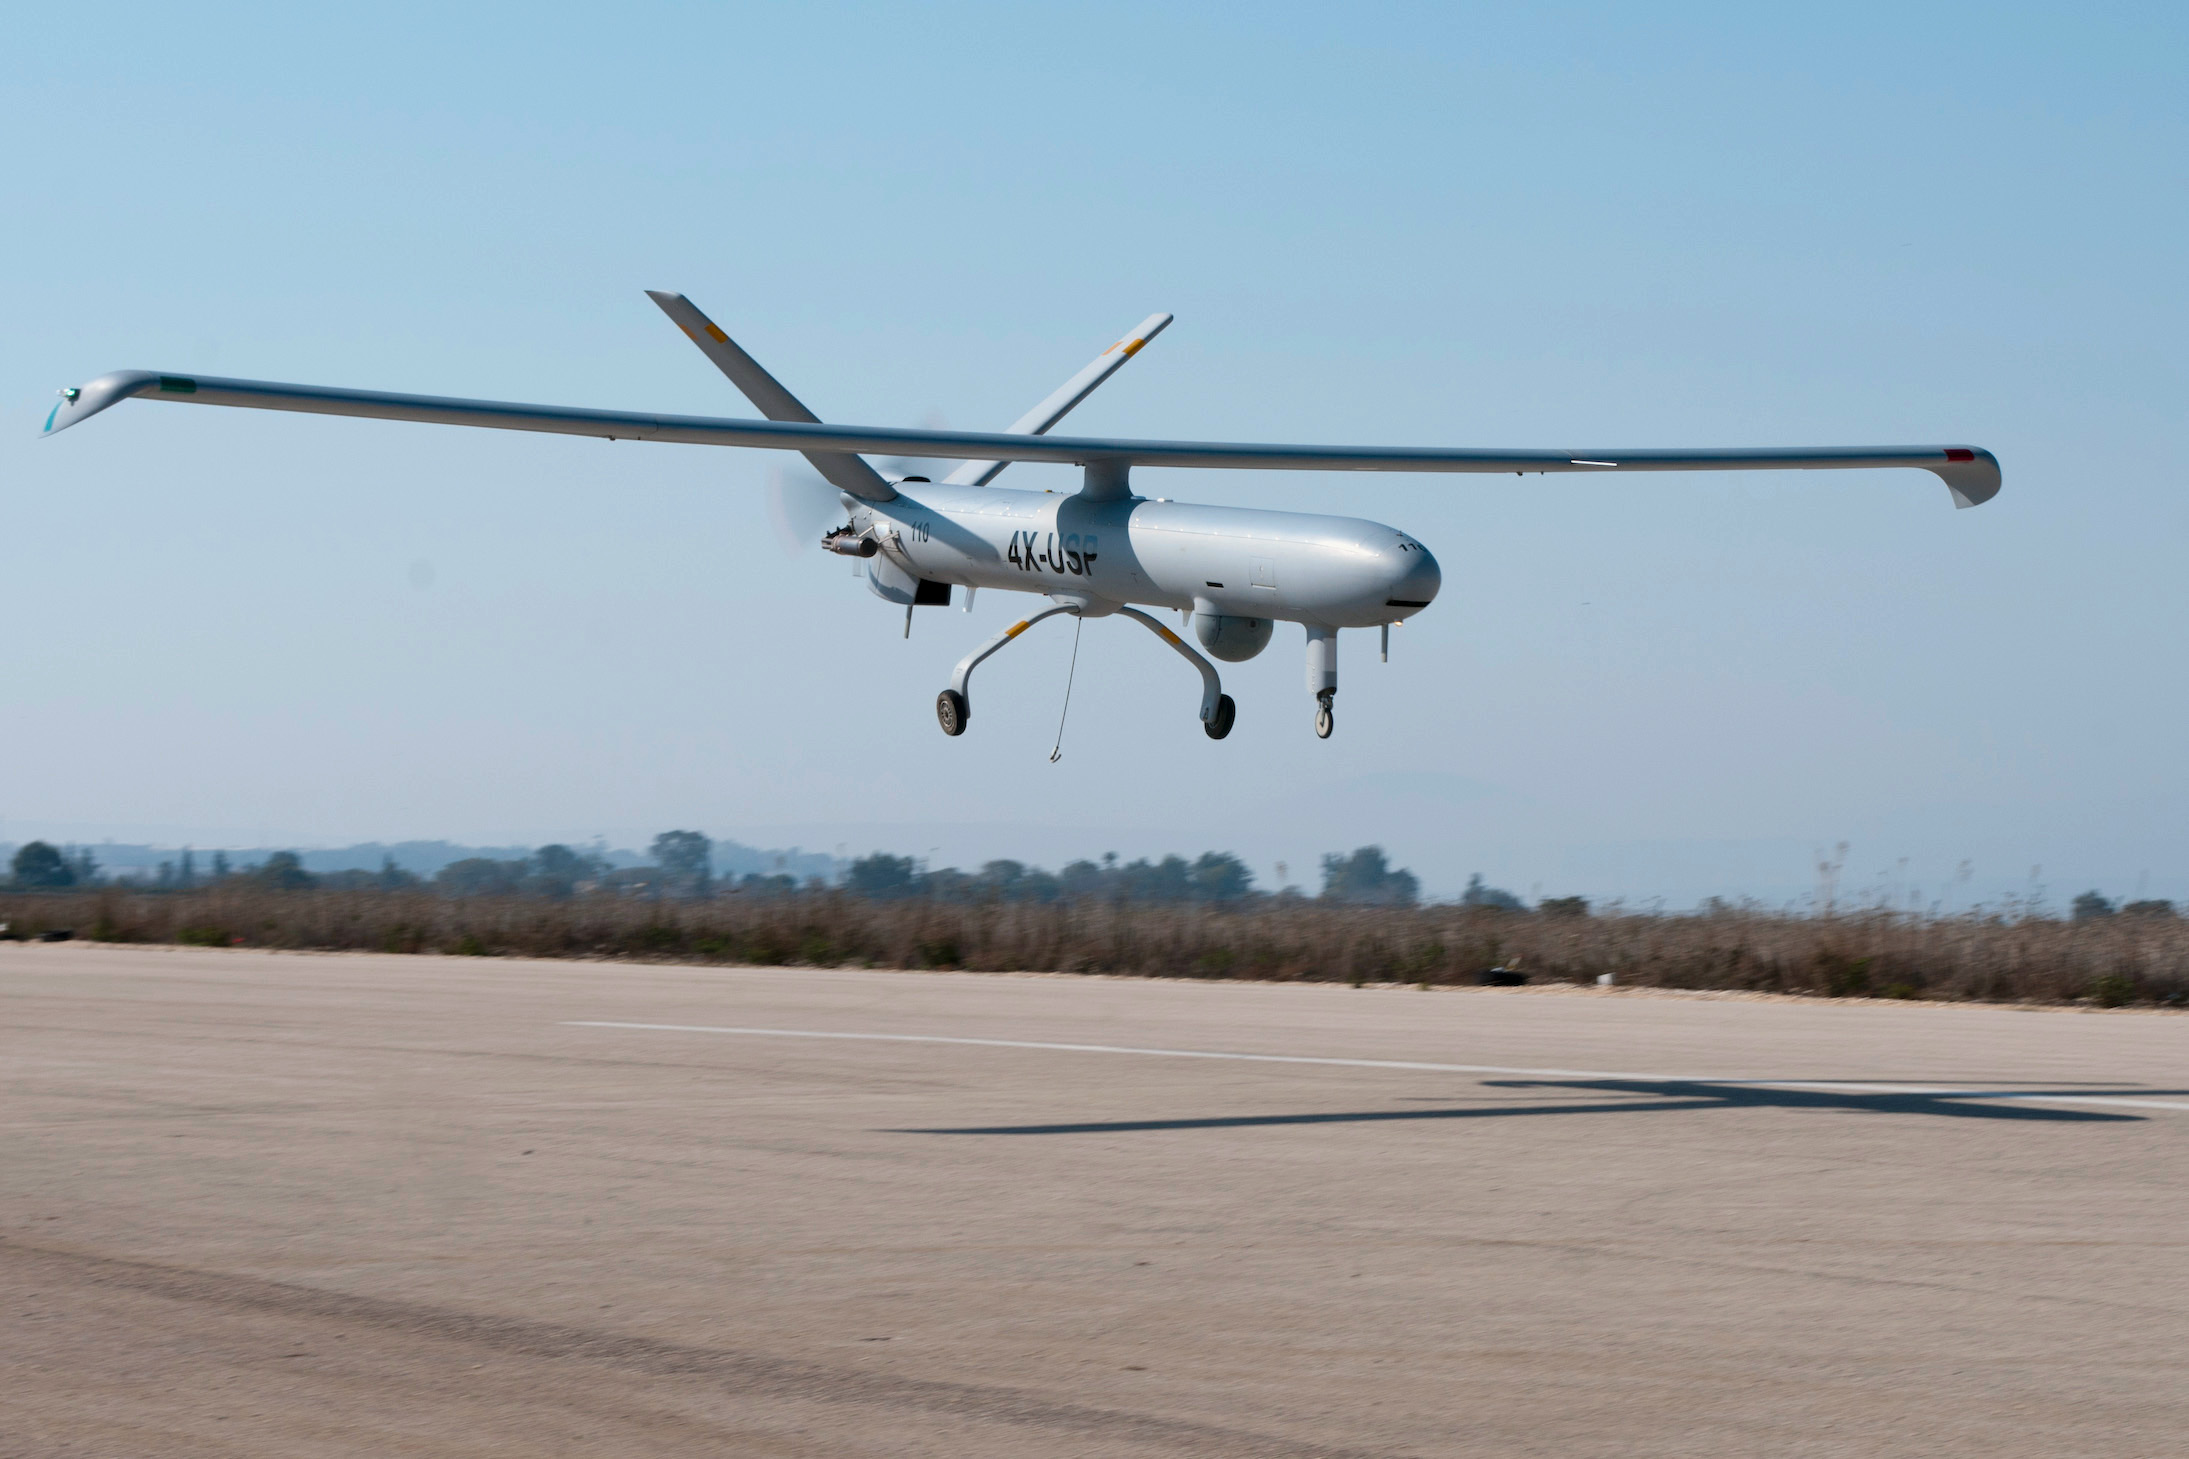
An emergent feature of the modern-conflict, especially in Ukraine, is the technological development and implementation of drone technology where the Ukrainian’s now have the world’s first unmanned systems force with its own human coronel- read more in September’s defence themed blog. In recent days, Ukrainian forces have taken the fight into Russian territory occupying part of the Kursk Oblast.
Stock-market Correction
In addition, there was also a stock-market correction in early August, which concentrated minds in global financial markets over its causes and extent. Whether it was a portend of a recessionary future in 2025 or a timely correction, especially for those massive technology behemoths, dubbed the magnificent seven. By mid-August markets staged a powerful market bouncy back albeit with conflicting views over economic strengths weighed against perceived weaknesses.
The initial causes for the correction were figures on US manufacturing output and underwhelming employment figures for July. These heightened fears of a possible US recession and that the Federal Reserve was too hesitant in cutting interest rates. This combined with a (small but significant) rise in interest rates from the Bank of Japan, convincing investors the long and much-loved Yen carry-trade was finally over.
Therefore, it was necessary to unwind short and long positions in currency trades and stocks, particularly heavily bought US technology stocks, including AI chipmaker Nvidia.
The very sharp and fast-moving correction does highlight the speed and ferocity of computer-driven trading programmes triggered by critical or perceived to-be critical market data being released. The pace of the bounce back, although less dramatically reported, suggests how well-positioned long/short strategic traders can benefit over more jittery leveraged long-only investors who need to liquidate positions once sentiment turns, and margin calls materialise. Regardless of early August’s sell-off the stock market, the US especially, has still performed positively so far in 2024, thus less leveraged long-term investors adjust to suit.
This momentum reversal as suggested by a leading US Equities investor, Putnam Investments, creates, ‘a sharp reaction’ and added ‘there’s a saying: stability breeds fragility’ and that the market was ‘testing’ people’s knowledge over what assets they own and if their strategy is robust (FT, 2024). You could say the market got lively to see who would scare-off first and why.
In wider analysis, after clearing out short-term leveraged retail investors, further consideration concerns the trending downwards of US growth. Although is that not to be expected with rates finally starting to fall and post-pandemic stimulus spending trailing-off? This argument over the robustness of the US growth shall provide the fractiousness for future market volatility in the coming months.
Resilience of the US Economy
The December 2023 blog discussed the resilience of the US economy which had reported growth of over 5% in Q3 of 2023. It’s arguable that if the US economy dropped to a less inflationary inducing growth rate of say 3% during 2024 with reducing interest rates. This hardly invokes a recession; indeed, it suggests the hoped for post-pandemic economic soft landing for the economy is materialising.
However, there’s always concerns the technology titans, such as Apple, Microsoft or Alphabet, who reported less stellar quarterly growth than the market had become accustomed to, are the arbiters of slower growth ahead. Notably, these stocks have seen stellar growth and market valuation in recent years. Furthermore, it says little of other sectors in the economy- US or its global trading partners.
Will there be a rotation from growth in highly valued technology stocks towards value-orientated defensive or dividend paying cyclical stocks, such as pharmaceutical or mining? Can London’s stock market finally shake off its moribund performance of recent years in such circumstances-see April’s blog?
With a chaotic geo-political agenda, it’s impossible to know. However, defence companies have large order books and long-term contracts and there’s no shortage of unresolved conflicts. Obesity or threats of infectious diseases persist which anchors pharmaceutical research and demand for its products. Much-needed housing and renewable infrastructure underpins metal demand for the foreseeable future.
Furthermore, regardless of AI over-hype, the technology will continue to be improved and adopted to productive uses with decarbonisation investment to counter climate change and implement government policies and co-ordinated global initiatives.
If financial markets do have concerns for progress over the continuing resilience of the US consumer, the over-valuation of technology stocks or winding-down of the Yen carry-trade and timing of rate cuts. This should also be evaluated with concerns with longer term fiscal issues like the US debt levels and domestic politics. The fractious US presidential elections and consequent outcomes for continuing military assistance for Ukraine, or Middle East peace resolutions and protectionist trade-disputes and tariff wars or worse with China, especially over advanced AI chips.
Regarding long heard US comments over defence spending all European countries, including the UK, need to increase their budgets to 2% of GDP or preferably more. Reliance on the US peace-keeping efforts for ever is no longer sufficient regardless of who wins in November’s US presidential election.
It also a wonder why the democrats don’t make more political capital over their border proposed deal by Mexico where travellers from around the world arriving in Mexico will require a 10-year passport to enter and travel through Mexico to the USA or face being returned to their point of entry (often countries to south of the Mexico). This ‘virtual’ wall would certainly be an effective barrier to unwanted illegal migrants entering the US – will it be a priority deal to complete for a new administration (CNN, 2024)?
Volatility is Back
In short life goes on and from a trader’s perspective volatility is back. The smart trader can make money from long and short strategies, the experienced investor can trim post-growth stocks and re-allocate positions and the plain scared can retreat to cash or the coffee-shop to lick their wounds until next time. To guess whether markets will rise or fall in the next 12 months is for the birds, the brilliant or the plain lucky.
For everyone else do your own research and take your positions. Relax, breathe, as life is for living with summer holidays to be savoured and a less frantic pace welcome.
LDC.
P.S. Future blogs will be forthcoming on topics such as the UK Labour government’s plans for house building, the rise and rule of the professional and managerial classes, and as mentioned defence and security issues so until then it’s Rheinmetall ago-go. Although its stock price dipped recently over continuing defence funding from Germany to Ukraine was queried- such is the precariousness nature of political discourse.
Reference and Further Reading–
Financial Times, (2024) ‘The Meaning of the Summer Sell-off,’ FT Big Read: US Equities by N. Megaw, M. Darbyshire, J, Franklin & L. Lewis, Financial Times Ltd 2024, London UK. Available Online at: The meaning of the market sell-off
(weekend edition 10/11th August 2024).
CNN, (2024), ‘Mexico’s President Seeks Agreement for US to Send Deportees Directly to Countries of Origin’ by A. Alvardo, R. Flores, & R. Munoz-Ledo, 2024 Cable News Network, A Warner Bros. Discovery Company. Available Online at: Mexico’s president seeks agreement for US to send deportees directly to countries of origin | CNN
LDC Blog December 2023 That’s Resilience for You: US Q3 GDP Growth Revised Up from 4.9% to 5.2%
Photos
Keir Starmer gives his first speech as Prime Minister from Downing Street. Author Parrot of Doom

Elbit Systems Hermes-450 unmanned aircraft takeoff Author Nehemia Gershuni-Aylho
https://en.wikipedia.org/wiki/Unmanned_aerial_vehicle#/media/File:NGP_DSC_0364.jpg

Olympic rings on the Eiffel Tower, Paris 2024 Author ibex73
https://commons.wikimedia.org/wiki/File:Olympic_rings_on_the_Eiffel_Tower_2024_(12).jpg

Official portrait of Vice President Kamala Harris. Author Lawrence Jackson
https://commons.wikimedia.org/wiki/File:Kamala_Harris_Vice_Presidential_Portrait.jpg
